
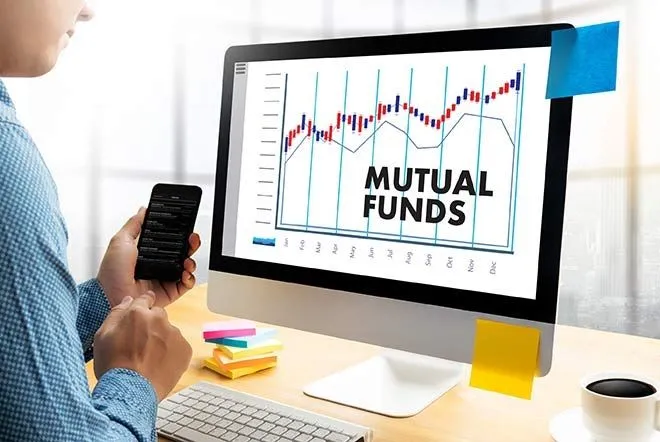
India’s investment landscape has undergone significant changes as digital platforms make mutual funds more accessible to individual investors. Transactions that once required extensive paperwork can now be completed through online systems, while portfolio information is increasingly available through mobile applications.
However, technology has not eliminated the need for responsible financial product distribution. Individuals exploring Kfintech MFD services may discover how digital infrastructure supports transaction processing, investor records, and administrative activities. Understanding these functions is particularly important for professionals entering the mutual fund distribution business.
Why Distribution Still Matters
Online investment platforms allow customers to access products independently, but many investors still need assistance understanding documentation, scheme categories, and transaction procedures. Distributors can help customers navigate these administrative requirements while explaining product information within their permitted professional responsibilities.
The relationship becomes particularly valuable when investors require assistance with account updates, nomination records, or other operational matters. Reliable service can encourage long-term engagement without creating unrealistic expectations about investment performance.
From Paperwork to Digital Operations
Traditional investment distribution involved physical application forms, document collection, and manual follow-ups. Digital infrastructure has reduced several administrative difficulties by supporting electronic records, online transactions, and more efficient communication.
Nevertheless, technology does not remove every operational responsibility. Distributors must maintain accurate information, monitor transaction status, and address discrepancies promptly. Digital efficiency becomes meaningful only when supported by dependable processes and responsible customer service.
Understanding the Registration Process
Professionals interested in becoming a mutual fund distributor must understand the applicable certification and registration requirements. These generally involve prescribed qualifications, registration with the Association of Mutual Funds in India, and an appropriate AMFI Registration Number.
Registration alone does not automatically permit distribution of every mutual fund scheme. Distributors must also meet relevant asset management company empanelment requirements and follow applicable regulatory guidelines before undertaking business activities.
The Importance of Investor Documentation
Accurate investor records are fundamental to effective mutual fund servicing. Incorrect personal information, outdated contact details, or incomplete documentation can create complications during transactions and account-related requests.
Distributors should encourage customers to verify important details and complete required procedures through authorised channels. Careful record management can reduce administrative delays while supporting transparency in the customer relationship.
Understanding Income and Business Expenses
Mutual fund distribution businesses commonly earn commissions associated with eligible regular-plan investments, subject to applicable arrangements and regulations. Actual earnings depend on factors such as assets under distribution, scheme categories, and prevailing commission structures.
Business owners should also account for technology expenses, staffing, customer acquisition, and compliance-related costs. Revenue projections need to reflect realistic operating conditions rather than assuming that every new customer will immediately generate substantial income.
Building Relationships Through Education
Customer relationships are stronger when investors understand the products they purchase. Explaining concepts such as market risk, investment horizons, and expense ratios helps individuals develop realistic expectations.
Educational communication should remain factual and avoid presenting historical returns as guaranteed outcomes. Distributors must also respect the distinction between permitted distribution activities and regulated investment advisory services, which have separate requirements.
Choosing Operational Support Carefully
Different service providers offer varying levels of technological integration, transaction assistance, reporting facilities, and customer management capabilities. The suitability of these arrangements depends on an individual distributor’s business requirements.
Before selecting operational partners, professionals should examine service accessibility, available integrations, data security, and support procedures. Comparing practical features can be more valuable than choosing a provider based solely on promotional material.
Preparing for Sustainable Expansion
A growing customer base creates additional responsibilities. Without organised records and consistent servicing procedures, expansion can lead to missed communications, operational errors, and customer dissatisfaction.
Distributors can prepare for growth through clear workflows, periodic staff training, and dependable digital systems. Long-term business development should prioritise service quality and regulatory compliance alongside commercial objectives.
Conclusion
Mutual fund distribution continues to evolve as technology transforms investment transactions and customer expectations. Digital systems can improve operational efficiency, but professional knowledge, accurate documentation, and responsible communication remain essential to the business.
Individuals entering this sector should understand registration requirements, evaluate infrastructure carefully, and establish realistic financial expectations. Educational comparisons available through finec.in can help prospective distributors explore different business arrangements and service models. Ultimately, sustainable growth depends on combining efficient technology with transparent practices and consistent customer support rather than relying exclusively on digital convenience.